Situation and difficulty
The clients held a diversified growth portfolio but lacked a defined liquidity sleeve for the transition years. They intended to retire within five years while still funding large discretionary expenses (extended travel, supporting adult children’s education deposits). Every market decline triggered anxiety about “having to sell at the wrong time,” which in turn led to ad hoc cash raises from growth assets—precisely the behaviour their original allocation was meant to avoid.
Compounding the problem, they maintained a partial offset mortgage they might pay down aggressively, which would reduce liquidity further. Tax considerations on embedded gains in a managed fund made sudden liquidations unattractive. They needed a ladder that separated known spending from uncertain longevity risk without freezing the entire portfolio in cash.
Our approach
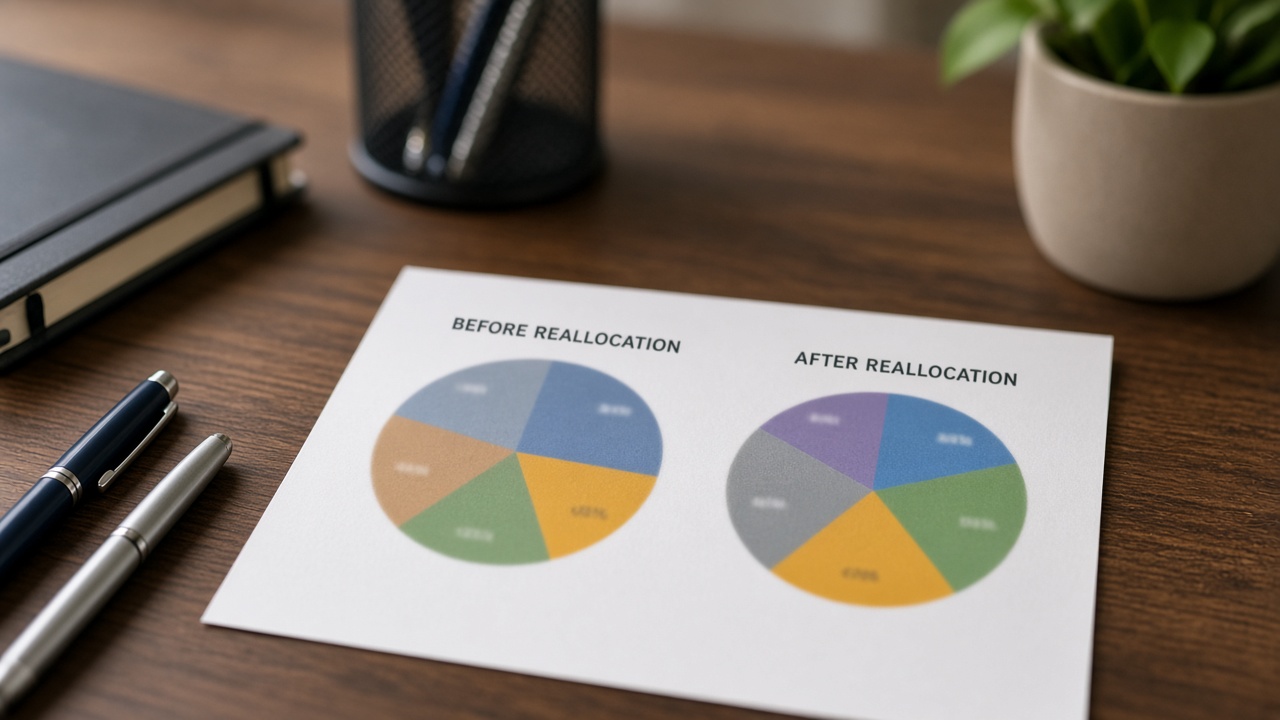
We rewrote the investment policy statement to recognise three horizons: (1) 36 months of essential spending in cash and short-duration defensive holdings; (2) years 4–10 funded by a balanced sleeve with explicit maximum drawdown language; (3) longevity and legacy assets in growth with rebalancing bands widened only after horizon one was fully funded.
Implementation was staged over four quarters: first redirecting new contributions and dividends into the liquidity sleeve, then trimming overweight growth positions on strength rather than in downturns. We modelled mortgage payoff as a scenario branch rather than a default—showing how aggressive payoff would shift the liquidity ratio and what travel plans would need to defer.
Measures and controls
- Monthly liquidity ratio report against the 36-month target.
- “No sell” rule for growth assets during liquidity breaches unless IPS committee (client + adviser) documented exception.
- Tax lot schedule reviewed with their accountant before each planned trim.
- Quarterly narrative tying market moves to horizon buckets, not headline indices.
Outcome
At engagement end, the liquidity sleeve covered 34 months of essential spending (target 36, funded by scheduled dividend inflow within 60 days). The clients reported fewer reactive calls during a mid-year equity pullback because drawdowns were framed against the growth sleeve only. Travel remained funded from horizon two without forced sales. Mortgage payoff was deferred twelve months with documented rationale. Past cases are not indicative of future results; your circumstances may differ.